Original Coverage & Source Attribution: finviz.com
MARA Holdings heads into its third-quarter report with a striking disconnect between the story management is telling and the verdict the market has delivered. Last quarter, the company laid out a far larger power ambition, roughly 4.8 gigawatts on a pro forma basis, and promised that the second half of the year would be about execution. Since then the stock has fallen 38% while the S&P 500 slipped just 2%. This report is the first real chance to show whether that execution is happening, or whether the platform expansion remains a slide deck sitting on top of a Bitcoin-dependent income statement.
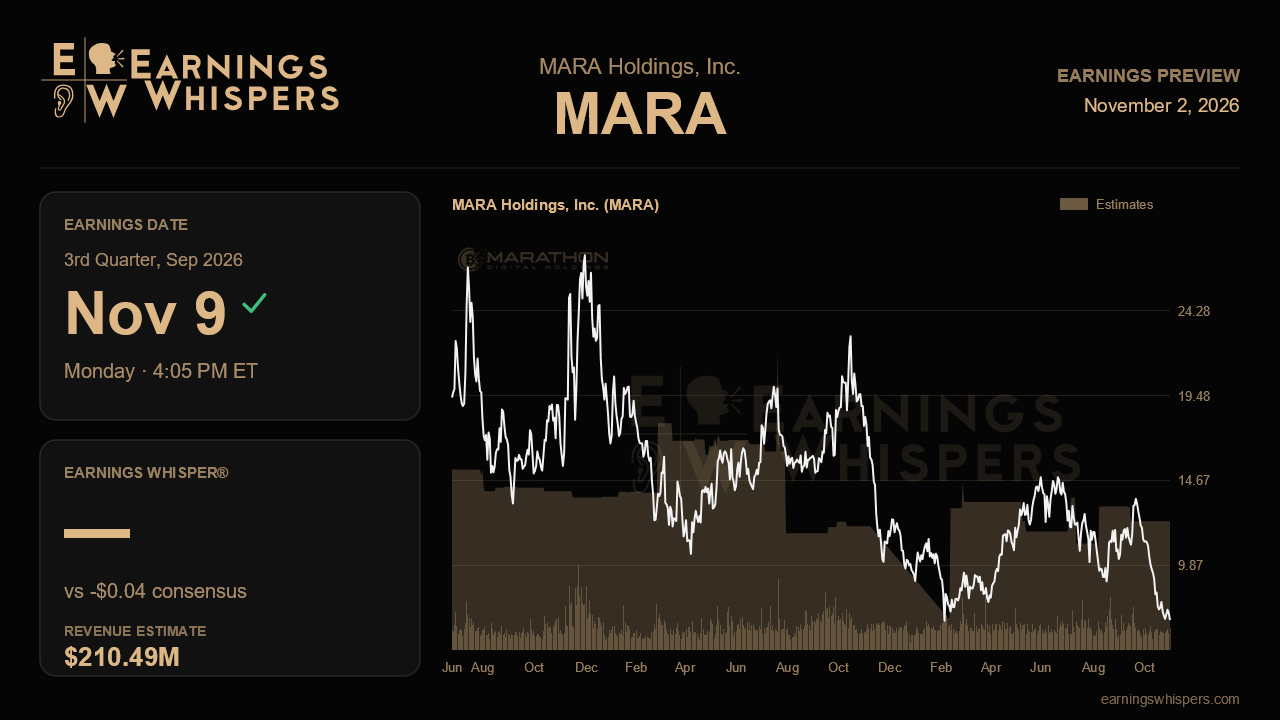
The Street is looking for a loss of $0.04 per share on revenue of about $210.5 million. That revenue figure would be down 16.6% from the year-ago quarter, so the business is still contracting on an annual basis, but it would also represent a healthy step up from the $174.9 million reported last quarter. The expected per-share loss is a sharp improvement from the $0.70 loss last quarter and the $0.32 loss a year ago. Investors should treat that EPS figure cautiously. MARA’s bottom line is dominated by mark-to-market swings on its Bitcoin holdings, which drove most of last quarter’s $611.3 million net loss, so the headline number will say more about where Bitcoin closed the quarter than about operating performance. Management has not issued formal financial guidance, which leaves the strategic milestones as the more meaningful scorecard.
The most important of those is leasing. Management said tenant demand had exceeded its expectations and reaffirmed confidence in signing at least two Starwood leases before year-end. With the calendar running short, any signed agreement, or at least concrete detail on counterparties, capacity and timing, would go a long way toward validating the narrative. Silence or vaguer language would suggest the conversion from interest to contracts is harder than advertised. Close behind is Longridge. Management quantified the deal at roughly $144 million of annualized EBITDA with about 70% of output contracted, the first genuinely non-Bitcoin cash flow in the portfolio. Progress on FERC approval and closing would confirm that diversification is arriving on schedule; further delay would push that support further out. The Matagorda site, with up to roughly 2 gigawatts of potential, adds another regulatory question tied to the ERCOT audit process.
The balance sheet deserves equal scrutiny. Bitcoin holdings fell to 35,577 last quarter from 53,822 at the end of the prior fiscal year, and the share pledged as collateral jumped to 54% from 28% just one quarter earlier. Layered on top of roughly $900 million in assumed Longridge debt and $600 million in new Bitcoin-backed facilities, that leaves less room to absorb a weaker coin price. Credit to management for avoiding equity dilution, but investors will want to see whether holdings and collateral levels stabilized. On the mining side, hash rate dipped sequentially to 70.3 exahashes as legacy machines were retired, while energy cost per coin mined rose with network difficulty. A rebound in hash rate and continued gains in share of network rewards, which reached 5.9%, would show the core business is still sharpening.
Sentiment has edged modestly positive after leaning bearish ahead of the last report, yet the stock trades at $6.77, well below its 200-day average of $10.80 and just above its post-earnings low of $6.45. That combination suggests some investors see value in the asset base while the tape still reflects deep skepticism, meaning a credible update could land on a low bar.
Ultimately, this quarter hinges on whether MARA can show tangible conversion of its power portfolio into contracted revenue. Signed leases and a clear Longridge path would support the thesis that the company is becoming more than a leveraged bet on Bitcoin. Without them, the growing debt load and pledged holdings will likely keep the market focused on the risks rather than the ambition.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.